Regulatory fragmentation, restricted banking access and local payment preferences remain major obstacles to international transactions. At FX.world Rome 2026, five payment industry professionals discussed how financial institutions and fintech providers can make cross-border payments faster, more accessible and easier to manage without compromising security.
Cross-border payments have become faster and more technologically sophisticated, yet moving money between markets remains far from straightforward. Regulatory differences, restricted access to banking services and the challenge of integrating local payment methods continue to complicate international expansion.
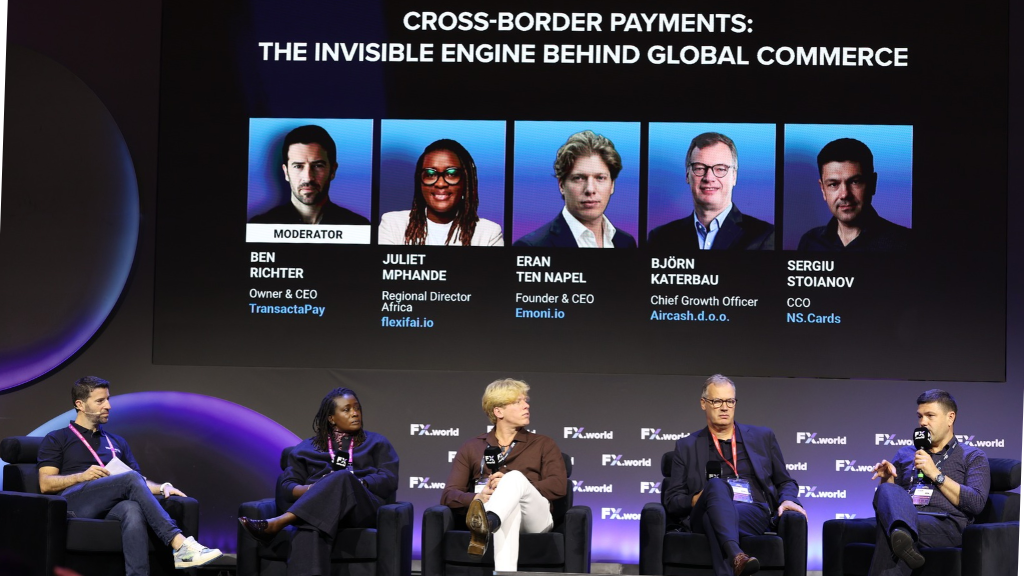
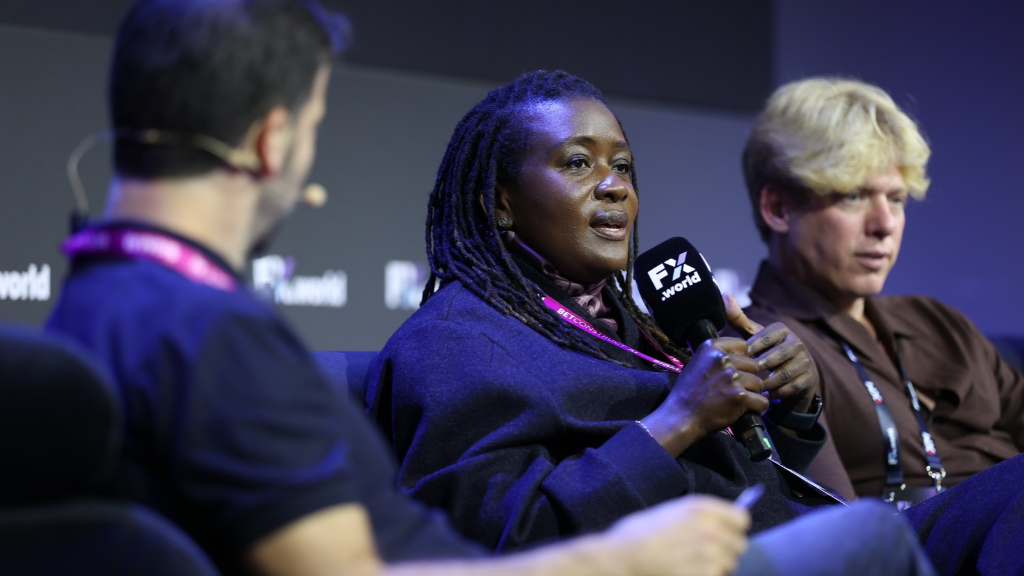
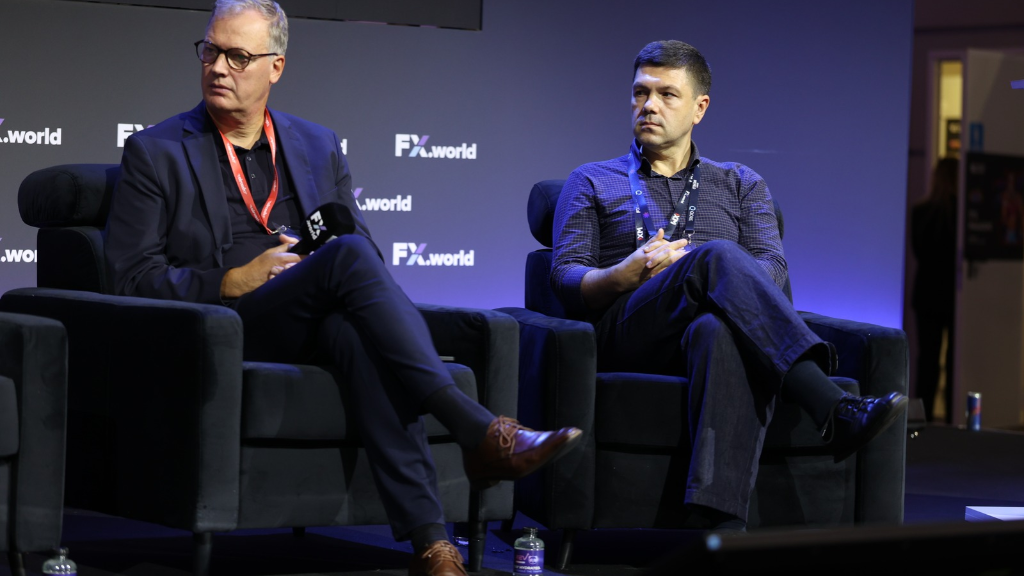
These barriers were central to Cross-Border Payments: The Invisible Engine Behind Global Commerce, a panel held on 3 November at the Global Finance Stage during FX.world which took place in Rome, on November 2026.
Moderated by Ben Richter, Owner & CEO of TransactaPay, the discussion featured Juliet Mphande, Regional Director at FLEXIFAI; Eran ten Napel, CEO & Founder of Emoni; Björn Katerbau, Chief Growth Officer at Aircash d.o.o.; and Sergiu Stoianov, CCO at NS.Cards.
While the speakers approached the subject from different markets and business models, a common challenge emerged: technology can connect payment systems across borders, but successful implementation still depends on regulation, banking relationships and an understanding of local markets.
Banking access remains a barrier for legitimate businesses
For Eran ten Napel, one of the most pressing problems is the difficulty certain businesses face when trying to establish reliable banking relationships.
He explained that traditional banks and electronic money institutions (EMIs) increasingly rely on automated onboarding systems designed to process relatively straightforward applications. More complex businesses, including those operating in gaming and financial trading, often require additional due diligence that these systems cannot adequately handle.
As a result, legitimate merchants may struggle to obtain banking services even when they are willing to meet the necessary compliance requirements.
Ten Napel argued that financial institutions need onboarding and transaction-monitoring procedures tailored to different business categories. AI can make document processing and verification more efficient, but he warned against removing people from the process entirely.
For businesses subject to enhanced due diligence, direct communication with a compliance specialist remains particularly valuable. A human representative can explain documentation requirements, resolve uncertainties and guide applicants through procedures that automated interfaces may struggle to accommodate.
The challenge, he suggested, is not to weaken compliance standards but to apply them more intelligently.
Why Africa demands a local approach to payments
The importance of understanding individual markets was particularly evident in Juliet Mphande’s assessment of payment expansion across Africa.
Mphande cautioned against treating the continent as a single market, pointing to differences in consumer behaviour, regulatory frameworks and payment infrastructure across its countries.
A payment solution designed for one market may encounter very different conditions elsewhere. She contrasted the prevalence of bank transfers in Nigeria, mobile money in Kenya and cash-based payments in Egypt to illustrate how consumer preferences shape the viability of financial products.
Her central message was that international companies cannot assume a payment model developed in Europe will translate directly into African markets.
Instead, entering a new jurisdiction requires research into local conditions, payment habits, existing infrastructure and regulatory requirements.
Mphande also highlighted regional efforts to improve payment interoperability, alongside the importance of working with locally established and licensed partners.
These relationships can help international merchants understand how particular markets operate rather than relying on a uniform expansion strategy.
The commercial opportunity, she argued, lies in recognising these differences and building services around them.
Embedded finance brings banking, cards and crypto closer together
Sergiu Stoianov examined how embedded finance could simplify the way international businesses manage money.
He described two possible approaches. The first involves bringing banking services, payment cards and cryptocurrency solutions together within a single platform, allowing merchants to access different financial instruments without managing multiple disconnected systems.
The second involves businesses integrating financial services directly into their own platforms, giving customers additional ways to receive, manage or spend funds.
Stoianov suggested that these integrated services could also strengthen customer relationships by making a platform useful for a wider range of financial activities.
However, he identified an important obstacle: not every financial provider currently offers the technical capabilities required to embed its services into third-party platforms.
The discussion also considered whether cryptocurrencies could eventually replace conventional banking infrastructure.
Rather than presenting the two systems as mutually exclusive, Stoianov envisaged closer integration, with crypto services and traditional financial products increasingly available through the same platforms.
Such an approach could allow businesses to combine different payment methods according to their operational requirements, although widespread implementation would still depend on provider support and regulatory conditions.
Cash-to-digital payments show how regulation can drive innovation
Björn Katerbau offered a historical perspective on the relationship between payment innovation and regulation.
Looking back to the early development of cash-based online payment services, he recalled a period when credit card penetration was relatively limited in markets such as Germany and Austria.
Consumers wanted to purchase goods and services online but frequently relied on cash. Cash vouchers and similar instruments emerged to bridge that gap, allowing physical money to be converted into electronic value for online transactions.
As regulatory requirements developed, providers faced increasingly demanding customer identification and verification obligations.
Katerbau explained that these changes made payment operations more complicated but also encouraged investment in new technology, particularly solutions capable of verifying customers both online and at physical points of sale.
He pointed to debates over identification requirements in Germany as an example of how regulatory proposals could accelerate technological development while raising questions about consumer privacy.
For Katerbau, regulation is therefore not simply an obstacle to innovation. It can also become a catalyst, provided policymakers recognise the practical needs of consumers and payment providers.
Can compliance and customer experience work together?
The relationship between regulation and operational efficiency returned during an open discussion involving the full panel.
The speakers acknowledged that stronger compliance requirements have helped improve payment security, but questioned whether the resulting processes have become unnecessarily burdensome for legitimate businesses.
Ten Napel highlighted the potential for AI-assisted document analysis to shorten transaction reviews that might otherwise leave businesses waiting for extended periods before making essential payments.
Mphande, meanwhile, emphasised opportunities for payment companies to engage with regulators and contribute to the development of market-specific solutions.
Katerbau returned to the importance of interoperability, noting that businesses entering markets such as Brazil and India must account for established domestic payment systems, including Pix and UPI.
Stoianov warned that excessive friction could encourage some businesses to seek alternative payment arrangements, underlining the need to balance security, reliability and transaction speed.
Across these perspectives, the discussion pointed to a common principle: effective regulation should protect the financial system without unnecessarily restricting access to legitimate payment services.
The next step: Making international payments feel local
Looking ahead, the panel’s closing predictions focused on interoperability, faster settlement and closer integration between financial technologies.
Among the possibilities discussed were payment platforms capable of connecting multiple regions through a single API, the combination of local collection methods with blockchain-based international settlement, and stronger connections between cryptocurrency and card payments.
Another ambition was to make cross-border transfers as straightforward for customers as domestic transactions.
None of these developments would eliminate the need for regulatory compliance or local market expertise. Rather, the discussion suggested that the next generation of cross-border payments will depend on how effectively financial institutions and technology providers combine these elements.
The central challenge for the industry is therefore not simply to move money faster. It is to build infrastructure that allows businesses to operate across borders without having to navigate an entirely new set of obstacles with every market they enter.
The conversation will continue at FX.world Rome in 2027, with the summit moving to May as part of the event’s updated calendar. For more details on the new schedule and what lies ahead, read the announcement.